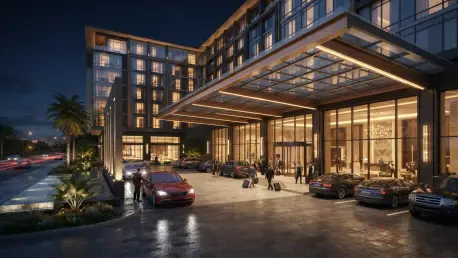
InterContinental Hotels Group reported a striking six point nine percent increase in revenue per available room across its American portfolio during the third quarter of 2026. This financial milestone reflects a broader hospitality landscape that has fundamentally shifted away from the stagnant predictions issued at the beginning of the year. While early economic forecasts suggested a marginal zero point six percent growth rate, the current market reality shows a performance nearly eleven times that initial projection. Travelers across the United States are encountering a hospitality sector that is no longer merely recovering from past disruptions but is actively expanding its profit margins through record-high pricing. This surge is not a localized or temporary spike; instead, it represents a structural transformation within the industry where demand continues to outpace expectations. The gap between what analysts predicted and how consumers are actually spending has created a high-cost environment for all types of travel.
Holiday Travel: The Shrinking Booking Window
As the winter holidays approach, the pricing pressure is landing most heavily on those planning to travel for the Christmas season. Analysis from major travel pricing platforms indicates that hotel rates for late December are currently eighteen percent higher than they were during the same period in 2025. The average cost for a hotel room on Christmas night has climbed to approximately one hundred ninety-seven dollars, marking a significant increase for family-oriented travelers. This sharp rise in holiday costs is attributed to a massive influx of bookings that began earlier than in previous years, leaving less inventory for latecomers. While Thanksgiving night prices have remained relatively stable at an average of one hundred seventy dollars, they still represent a historic high for the holiday. Travelers who once relied on finding affordable options during the winter months are now finding that the baseline for holiday lodging has moved into a significantly more expensive tier.
The window for securing these accommodations is also closing much faster than previously observed in the American market. Industry experts have identified October 31 as a critical threshold for consumers seeking to avoid the most extreme price hikes of the year. Statistical data shows that travelers who secure their lodging before Halloween are more likely to lock in rates that align with current averages, whereas those who wait until November face rapid price escalations. This compression of the booking window is driven by dynamic pricing models that respond instantly to declining availability. As the supply of available rooms diminishes in popular destinations, these algorithms automatically adjust the rates upward to capitalize on the holiday rush. Consequently, the traditional strategy of waiting for last-minute deals has become increasingly risky. By the time November arrives, the most desirable properties have often reached eighty percent occupancy, triggering another wave of rate increases.
Financial Metrics: Measuring the Industry Boom
The financial health of the lodging industry is further validated by recent filings showing that major hospitality brands are thriving under these conditions. InterContinental Hotels Group, which operates nearly four thousand properties in the Americas, reported that its regional revenue per available room rose nearly seven percent in the third quarter alone. Brands such as Holiday Inn, Crowne Plaza, and Kimpton have seen occupancy rates reach a healthy seventy-four percent, representing a notable year-over-year increase. Furthermore, the average daily rate for these properties has climbed by almost four percent, indicating that consumers are willing to pay a premium for recognized brand names. These figures suggest that the demand for both leisure and corporate travel is remarkably resilient, even as the cost of a stay continues to climb. The ability of these large-scale operators to maintain high occupancy while simultaneously raising prices highlights a very strong consumer appetite for travel.
Broader industry standards provided by data firms like CoStar and STR confirm that this performance is consistent across the entire national market. During the month of October, the national occupancy rate stood at over seventy percent, with an average daily rate exceeding one hundred seventy-seven dollars. These metrics prove that even after the peak summer travel season concludes, the demand for lodging remains high, which prevents prices from falling back to previous levels. This sustained demand is partially driven by a robust corporate travel sector that has fully returned to pre-stagnation levels, filling rooms during the midweek periods that were previously difficult to book. When combined with a strong weekend leisure market, the result is a high floor for pricing that persists throughout the entire week. The consistency of these key performance indicators across different regions and price points suggests that the current high-rate environment is a nationwide phenomenon.
National Drivers: Events and Labor Challenges
The sustained high costs of hotel stays in 2026 are largely attributed to several converging national factors that have created an environment of extreme demand. The year has been defined by massive international events, including the FIFA World Cup and the extensive America 250 national anniversary celebrations. These events alone have generated an additional eleven million room nights compared to the previous year, placing an immense strain on the existing supply of hotel rooms. In many major cities, hotels are reaching full capacity months in advance, allowing operators to set prices at record levels without fearing a loss in occupancy. The sheer volume of international visitors arriving for these celebrations has introduced a level of competition for rooms that the U.S. market has rarely seen outside of a few specific gateway cities. This influx of global travelers has pushed domestic prices higher as the overall pool of available accommodations continues to shrink.
Beyond the impact of major events, the hospitality industry is also facing a structural cost crisis related to the domestic labor market. Recent shifts in immigration enforcement and a generally tightened labor pool have significantly reduced the number of workers available for hospitality roles. This labor shortage has forced hotel owners to implement substantial wage increases to attract and retain essential staff, including housekeeping, maintenance, and guest services personnel. Because labor represents one of the largest operational expenses for a hotel, these rising costs have created a much higher operational floor. Consequently, hotel operators have very little room to offer the kind of deep discounts that were common in previous years without risking their overall profitability. These increased overhead costs are passed directly to the consumer in the form of higher nightly rates, ensuring that the cost of a stay remains elevated regardless of seasonal fluctuations or promotions.
Digital Strategy: Advanced Revenue Management Systems
Technological advancements in revenue management have also played a significant role in maintaining the high pricing trends observed throughout the year. Modern hotel pricing systems now utilize sophisticated real-time data to adjust rates dynamically based on a multitude of variables, including local demand and historical patterns. Because demand remained consistently high throughout the first three quarters of 2026, these automated systems have effectively locked in higher rates for the final quarter. These platforms are designed to maximize the revenue generated from every single room by identifying exactly how much a traveler is willing to pay at any given moment. This data-driven approach removes much of the guesswork from the pricing process, allowing hotels to remain aggressive with their rates even during periods that might have seen price drops in the past. The widespread adoption of these technologies means that rates are more reactive to market strength than ever before.
The implementation of these sophisticated algorithms has effectively signaled the end of the traditional “fire sale” era for last-minute hotel bookings. Instead of lowering prices to fill the final few rooms in a building, modern revenue management software often raises rates as availability drops. This strategy capitalizes on the urgency felt by travelers who need a room on short notice, as the system recognizes that scarcity increases the value of the remaining inventory. For the average consumer, this means that the price of a room is likely to increase as the date of the stay approaches, rather than decrease. This shift in pricing philosophy underscores the necessity for proactive planning and early booking. By leveraging historical data and current booking velocity, hotels can predict when a specific market will reach a tipping point in occupancy, ensuring that they never leave money on the table. This results in a market where consumers must adapt to a less flexible pricing structure.
Local Variation: High Spikes and Market Dips
While national averages provide a useful overview of the broader market, city-level data reveals significant volatility that is often driven by localized events. For example, Detroit experienced a twenty percent surge in revenue per available room during mid-October, largely due to a massive industry convention that brought thousands of professionals to the city. Similarly, San Diego saw an eighteen percent increase in rates driven by local gatherings and seasonal events that tightened the local supply of rooms. These localized spikes demonstrate that for many travelers, the national economic climate is often secondary to the specific event calendar of their chosen destination. A single large conference or a regional festival can cause prices in a specific city to double or triple within a matter of days. This localized volatility means that travelers must be increasingly aware of the specific circumstances surrounding their travel dates to avoid paying a massive premium for their stay.
In contrast, some markets have shown significant declines in pricing, though these are often the result of high-base effects from the previous year rather than a general softening of demand. San Francisco recently saw a substantial drop in average daily rates, but this was primarily because the city was no longer hosting a massive global conference that had inflated prices during the same week in 2025. This type of volatility highlights the importance of comparing year-over-year data with a clear understanding of the specific events that drive occupancy. For savvy travelers, identifying these “off-years” for certain cities can provide opportunities to find relative value in an otherwise expensive national market. However, these opportunities are becoming more rare as major metropolitan areas work to fill their calendars with a constant rotation of events and conventions. The overall trend remains one of upward pressure, as the competition for high-value business events keeps rates high.
Looking Ahead: Strategic Travel Planning
The 2026 hospitality landscape was defined by an unprecedented resilience in travel demand that consistently defied initial economic skepticism and conservative growth forecasts. Throughout the year, the convergence of massive international celebrations and structural shifts in the labor market created a persistent high-rate environment. Hotel operators successfully leveraged advanced revenue management technologies to maintain record-high pricing, ensuring that every room was sold at its maximum potential value. This year proved that the American consumer’s priority on travel was not easily deterred by rising costs, as occupancy rates remained high across all major regions. The industry demonstrated a remarkable ability to adapt to rising operational expenses by passing those costs through to a willing market. As a result, the baseline for what constitutes a standard nightly rate has been permanently elevated, reflecting the new economic realities of the modern travel and hospitality sector.
Reflecting on these trends, travelers who navigated the 2026 market found that success required a fundamental shift in their planning strategies. Those who utilized early booking windows before the Halloween threshold effectively avoided the most severe dynamic pricing spikes of the holiday season. The industry moved toward a model where flexibility and timing became the most valuable tools for the consumer. Moving forward, travelers should prioritize destination research to avoid localized event spikes and consider visiting secondary markets that offer similar amenities at a lower price point. It was also beneficial to look for mid-week stays as corporate demand occasionally softened, providing small windows of relative affordability. The lessons of this year showed that while the era of low-cost lodging had largely passed, proactive research and tactical timing remained the best ways to manage travel budgets. Adapting to these high rates required a more disciplined approach to securing accommodations well in advance.